
Insurance for Elective Ultrasound: Usually No, 2026
You generally cannot use health insurance for an elective 3D/4D ultrasound performed only for keepsake images or a bonding experience. Coverage depends on medical necessity and your plan’s benefits, not whether the scan produces 3D or 4D pictures. A medically indicated ultrasound still requires a separate check of provider participation, authorization requirements, and your share of the bill.
TL;DR
Insurance for elective ultrasound generally excludes keepsake-only 3D/4D scans; medical necessity determines whether a scan qualifies for coverage.
A referral does not guarantee coverage, and an in-network provider does not make an excluded service covered.
HSA and FSA eligibility is separate from insurance coverage; a payment card approval does not establish eligibility.
The Ultrasound Concierge provides private diagnostic and elective ultrasound; confirm the appointment’s purpose before asking about insurance.
Can you use insurance for an elective 3D/4D ultrasound?
Generally, no: a keepsake-only ultrasound is not a covered medical service. A diagnostic ultrasound ordered to answer a clinical question follows a different coverage pathway, even when the equipment can also produce 3D or 4D images.
For patients considering The Ultrasound Concierge, which provides diagnostic and elective ultrasound, the first question is which type of appointment you need. Do not assume that offering both services means both qualify for insurance reimbursement.
Medically indicated diagnostic ultrasound
Best for: Answering a clinical question identified by your clinician
Insurance distinction: Coverage depends on plan benefits, medical necessity, and billing requirements
Benefit: Provides imaging for clinical evaluation
Limitation: An order alone does not guarantee payment
Elective 3D/4D ultrasound
Best for: A nonmedical keepsake or bonding experience, if you choose one
Insurance distinction: Keepsake-only imaging generally falls outside covered medical benefits
Benefit: Offers a personal viewing experience
Limitation: Does not replace diagnostic prenatal imaging
Check your 2026 plan documents before booking. A previous claim, a friend’s coverage, or a general statement that pregnancy imaging is covered does not establish coverage for your particular appointment.
Why this matters
The word ultrasound describes an imaging method, not an insurance benefit. Two appointments using similar equipment can have different purposes and different coverage decisions.
That distinction protects both your budget and your prenatal care. If you need an examination because of symptoms or a concern identified by your clinician, start with that clinician rather than substituting an elective session.
Choose the clinical pathway for a clinical question. A keepsake image cannot establish that all aspects of a pregnancy are healthy, and a reassuring viewing experience is not the same as a diagnostic interpretation.
Elective 3D/4D ultrasound: keepsake imaging, not diagnostic care
An elective session centers on viewing your baby or obtaining keepsake images without a medical indication for that examination. Wanting clearer pictures, sharing the experience with family, or learning fetal sex for a celebration does not by itself establish medical necessity.
The distinction is about purpose. A scan does not become medically necessary because it uses sophisticated imaging, takes place in a healthcare setting, or is performed by someone with clinical training.
For your 2026 appointment, ask the provider to describe the service clearly: elective viewing, diagnostic evaluation, or separately identified services. You need that description before an insurer can answer a useful coverage question.
Elective imaging also has a medical limitation. The FDA discourages fetal ultrasound performed solely to create keepsake images, and the American Institute of Ultrasound in Medicine discourages nonmedical use of obstetric ultrasound. Discuss an optional session with your prenatal clinician rather than treating more imaging as automatically better care.
Diagnostic ultrasound: coverage depends on the medical purpose
A diagnostic examination addresses a clinical question. Your clinician determines the indication, and the imaging service follows the requirements applicable to that examination.
Medical necessity is essential, but it is not the only coverage requirement. Your plan can also have rules about referrals, prior authorization, participating providers, covered settings, and claim documentation.
A diagnostic examination does not guarantee that your insurer pays the entire bill. Deductibles, coinsurance, copayments, and out-of-network rules are separate from the question of whether the service is covered at all.
If you are considering an elective visit alongside routine prenatal imaging, review how to combine a 3D/4D ultrasound with your OB’s anatomy scan. Keep the clinical examination and optional viewing experience distinct when discussing scheduling and coverage.
Why insurance coverage for ultrasound varies
Insurance for elective ultrasound is not determined by image quality alone. These factors explain why similar-looking appointments can receive different coverage decisions:
Medical purpose: A diagnostic examination answers a clinical question; keepsake-only imaging does not establish that purpose.
Plan benefits: Your contract identifies covered services, exclusions, and applicable medical-necessity requirements.
Provider network: Coverage for a service and participation by its provider are separate questions.
Authorization rules: Some examinations require approval before the appointment. Approval still remains subject to the plan’s terms.
Documentation: The order, clinical indication, and accurately reported service support review of a diagnostic claim.
Optional services: Keepsake images or other nonmedical extras do not automatically share the coverage status of a diagnostic examination.
Ask about all applicable factors together. Confirming only that a provider accepts your insurance leaves the central question unanswered: does your plan cover the exact service you are booking?
How do I check coverage before booking?
Use the same service description with the provider and insurer. Calling an elective session a pregnancy scan can produce a general answer that does not apply to the appointment you actually want.
Identify purpose. Ask whether the appointment is elective or diagnostic. If diagnostic, ask what medical question the examination will address.
Confirm service. Request the exact service description and, when applicable, the billing information the insurer needs. Do not choose a billing code yourself.
Check benefits. Ask your insurer whether that service is covered under your 2026 plan and whether a nonmedical or keepsake exclusion applies.
Check requirements. Confirm network status, referral rules, prior authorization, and any applicable member responsibility.
Keep records. Save the written benefit response, authorization information when required, and the reference number for your insurer’s conversation.
This sequence separates a covered benefit from a provider’s ability to submit a claim. It also gives you something specific to refer to if the information changes before your appointment.
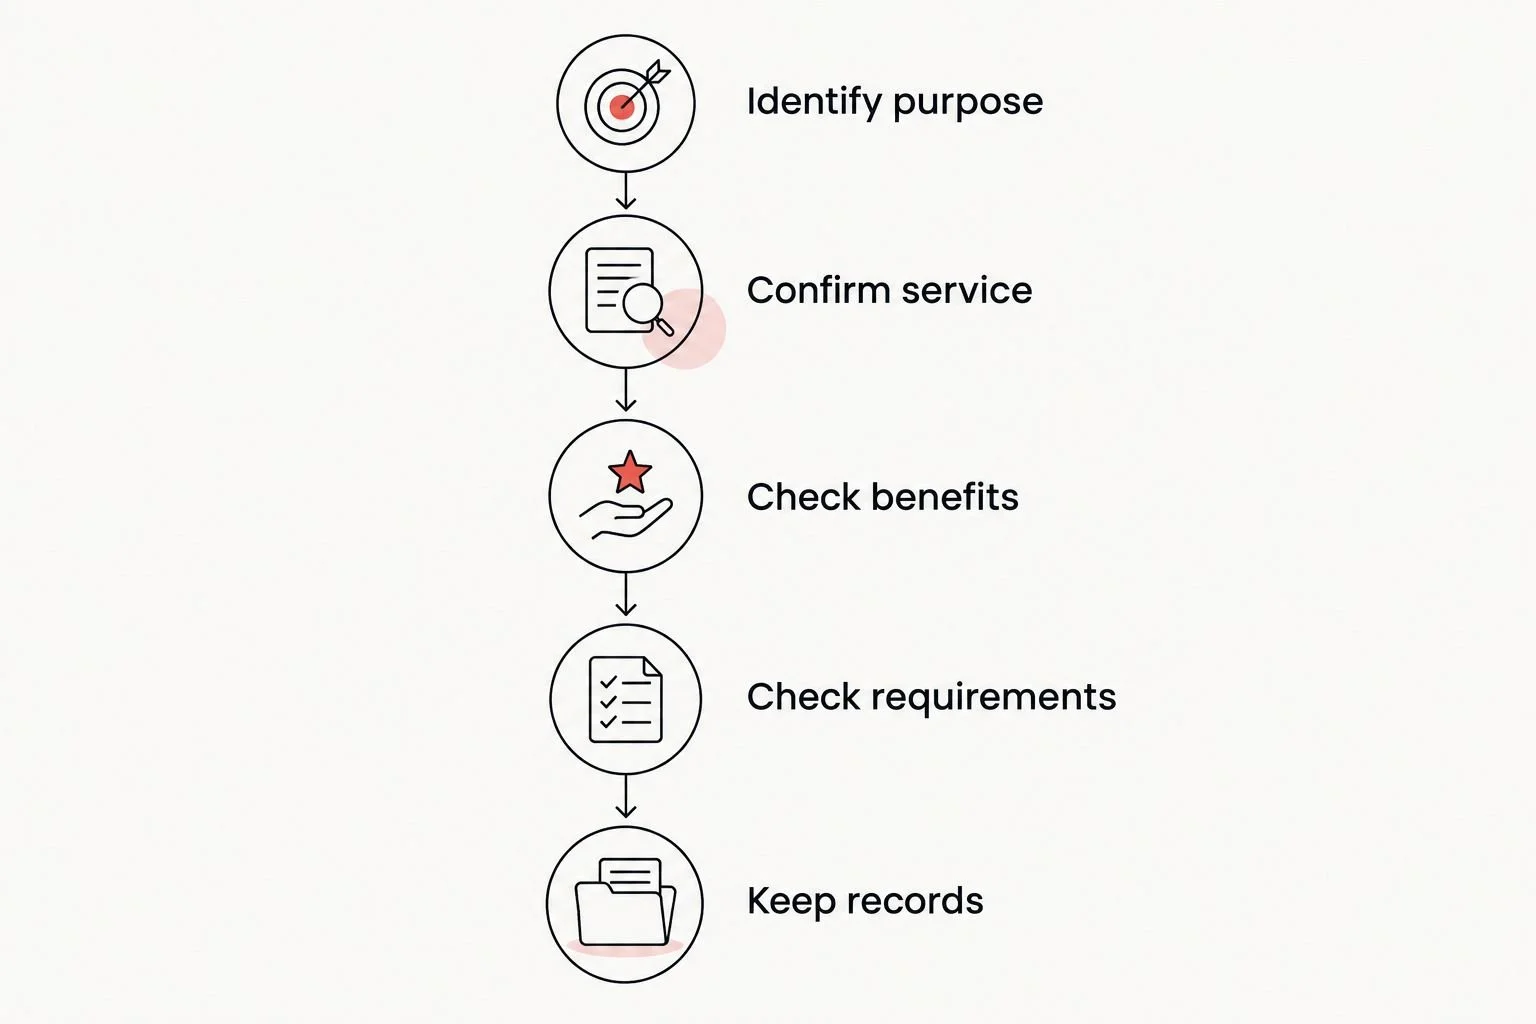
Start with the appointment’s purpose before asking whether insurance applies.
A benefit estimate or authorization is not an unconditional payment guarantee. The final claim must still match the service performed and satisfy the plan’s terms.
What should I ask my insurer and ultrasound provider?
Ask your insurer whether a keepsake-only 3D/4D ultrasound is excluded, rather than asking only whether pregnancy ultrasounds are covered. Then ask what changes if your clinician orders a diagnostic examination for a documented medical reason.
Useful questions include:
Does my plan cover this exact service for this stated purpose?
Is the provider participating in my specific plan, not just the same insurance company?
Do I need a referral or prior authorization before the examination?
Does coverage differ between the diagnostic examination and optional keepsake services?
What documentation is required if I submit a claim myself?
Can you provide the benefit explanation in writing?
Ask the provider whether it bills insurance for the appointment you are considering or treats that service as self-pay. Receiving a receipt is not the same as receiving an insurer-approved claim, and willingness to submit paperwork does not establish coverage.
Do not ask anyone to relabel an elective scan as diagnostic. Billing must accurately reflect the service and its medical purpose. If there is a genuine medical concern, involve your clinician and arrange the appropriate examination.
Does a doctor’s referral make an elective ultrasound covered?
No: a referral alone does not make a keepsake-only ultrasound covered. A referral documents a request for care; the insurer still evaluates the actual service against the plan’s benefits and medical-necessity rules.
If your clinician identifies a medical reason for imaging, book the corresponding diagnostic examination rather than assuming an existing elective booking changes status. Tell the provider about the order before the visit so the service can be arranged appropriately.
Can I use an HSA or FSA if insurance does not cover the scan?
Insurance denial does not determine HSA or FSA eligibility. These accounts follow tax rules for qualified medical expenses, which are separate from your insurance contract.
IRS Publication 502 describes medical expenses in terms of diagnosis, treatment, prevention, and related medical care. A purely nonmedical keepsake service should not be treated as eligible simply because it uses ultrasound equipment; confirm the service’s eligibility with your account administrator or a tax professional.
Can I appeal an insurance denial for an ultrasound?
You can request review of a denial under your plan’s appeal process. An appeal is most useful when a medically indicated examination was denied because of an administrative issue, missing documentation, or disagreement over medical necessity.
An appeal does not automatically turn an excluded keepsake service into a covered benefit. Read the denial reason first, then ask your insurer what evidence addresses that specific reason.
What if I have already paid for the appointment?
Start by obtaining an itemized receipt and a clear description of the service performed. If you believe the examination was diagnostic and your plan permits member-submitted claims, ask the insurer what documentation it requires.
Do not assume reimbursement because the appointment involved pregnancy or took place at an imaging provider. The service still needs to meet the plan’s coverage rules, and the documentation must accurately describe what happened.
For a denied diagnostic claim, compare the insurer’s explanation with the provider’s records. Ask for correction of an actual billing or documentation error—not a different description designed to make an elective service appear covered.
Choosing a private ultrasound appointment in Keller or Willow Park
The Ultrasound Concierge is for patients in Keller and Willow Park seeking private diagnostic or elective ultrasound. Its stated focus is a calm, personalized alternative to a clinical imaging center; that setting does not change an insurer’s coverage criteria.
The Ultrasound Concierge offers both diagnostic and elective imaging, so confirm which service fits your goal. A personal viewing experience and an examination ordered for medical evaluation have different purposes, even when both involve pregnancy ultrasound.
Before a 2026 visit, describe any clinician’s order accurately and ask how the appointment is handled. Choose diagnostic care for a medical question, and keep an optional keepsake decision separate from required prenatal care.
Clarify your ultrasound appointment
Review private diagnostic and elective ultrasound options in Keller and Willow Park.
FAQ
Can I use insurance for elective ultrasound in 2026?
Insurance for elective ultrasound generally does not cover a scan performed solely for keepsake images or bonding. Check your 2026 plan’s exclusions and confirm whether the exact appointment is elective or diagnostic.
Is a 3D or 4D ultrasound automatically considered elective?
No: the imaging format alone does not determine whether an ultrasound is elective. The examination’s clinical purpose and your plan’s requirements determine the coverage pathway.
Will insurance cover a gender-reveal ultrasound?
A scan performed only for a gender reveal generally does not establish medical necessity. Learning fetal sex during a covered diagnostic examination is different from booking an examination solely for that purpose.
Does an in-network ultrasound provider guarantee coverage?
No: network participation does not guarantee that a particular ultrasound service is covered. Your plan can exclude keepsake-only imaging even when a provider participates in the network.
Can I use my HSA or FSA card for a keepsake ultrasound?
Do not assume a keepsake ultrasound is an eligible HSA or FSA expense. Confirm eligibility with your account administrator or a tax professional; a card transaction approval does not establish that an expense qualifies.
Can an elective ultrasound replace my anatomy scan?
No: an elective keepsake session does not replace a diagnostic anatomy examination ordered as part of prenatal care. Keep the appointment recommended by your prenatal clinician.
Does The Ultrasound Concierge accept my insurance for a 3D/4D scan?
Confirm directly with The Ultrasound Concierge how your specific appointment is billed, then verify coverage with your insurer. Offering diagnostic and elective ultrasound does not establish insurance participation or coverage for either appointment.
One last thing
The most useful insurance question is not whether 3D/4D imaging is covered. It is whether your plan covers this service, for this medical purpose, from this provider.
Before booking in 2026, get that distinction clear and save the answer. If new symptoms or concerns arise, contact your prenatal clinician instead of using an elective session to decide whether you need medical care.